Business Driving & Tax
Youngtimer Addition to Taxable Income: Rules and Benefits
Updated
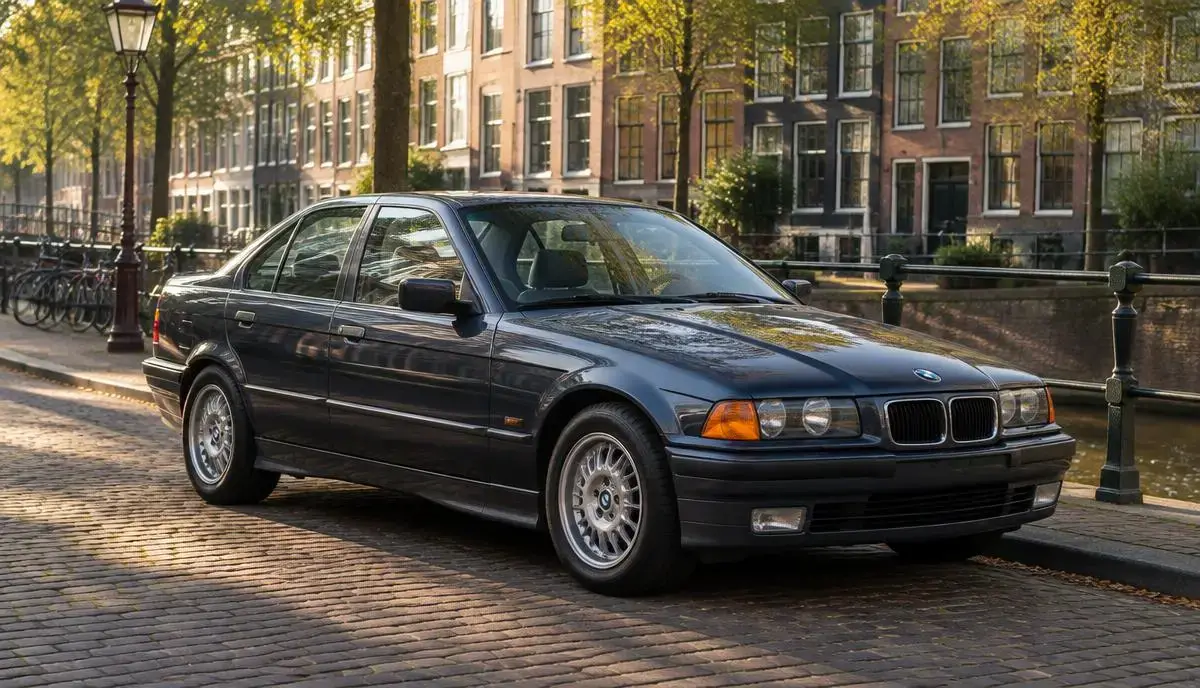
Driving a youngtimer for business is a popular option for entrepreneurs and sole traders. This is due to the unique youngtimer scheme within the tax system. It allows you to benefit from a representative car at favourable monthly costs.
What is the youngtimer scheme?
A car qualifies for the youngtimer scheme as soon as it was first registered exactly 15 years ago. From that moment, the addition to taxable income (bijtelling) for private use is no longer calculated based on the original catalogue value, but on the car's current market value, also known as its daily value (dagwaarde).
Tax advantages of a youngtimer
Because the market value of an older car is significantly lower than its original new value, the amount of the addition to taxable income is often more manageable. Furthermore, all business car expenses, such as maintenance and fuel, can be fully claimed as business costs. View more information on tax investment benefits to get the most out of your car choice.
- Addition to taxable income based on market value instead of catalogue value
- All car costs are tax-deductible from profit
- Wide choice of luxury and comfortably equipped models
Points of attention when buying a youngtimer
Although the tax scheme is attractive, you should take into account potentially higher maintenance costs or higher fuel consumption. Ensure that the market value is properly determined or substantiated each year. For specific conditions and tax implications, always consult the current rules of the Dutch Tax Authorities (Belastingdienst).
Which cars qualify for the youngtimer scheme?
The youngtimer scheme specifically applies to cars that have reached a certain age. To qualify as a youngtimer for tax purposes, a vehicle must be between 15 and 25 years old. This refers to the date of first registration on the road (date of first admission), not the production date. This age category ensures that a wide range of models, from popular family cars to more exclusive examples, can qualify for this favourable addition to taxable income scheme.
It is important that the vehicle physically still exists and is roadworthy. There are no further requirements for the car's make, model, fuel type, or mileage. It is therefore advisable, if interested in a specific car, to always check the exact date of first registration to ensure it falls within the applicable youngtimer age. This prevents surprises later during the tax processing.
- Vehicle is between 15 and 25 years old
- Reference date is the date of first registration
- No restrictions on make, model, or fuel type
- Car must be roadworthy
What about youngtimer maintenance and insurance?
In addition to the tax aspects, it is essential to consider the operational costs of a youngtimer. Older cars generally require more attention for maintenance than new models. Parts can be more expensive or harder to obtain, depending on the car type and rarity. It is advisable to have a thorough inspection carried out by a specialist before purchasing, to prevent unexpected and high repair costs.
Youngtimer insurance can also differ from that of a new lease car. Some insurers offer special youngtimer insurance policies, which are often more favourable than regular comprehensive policies, provided the vehicle meets certain conditions, such as a valuation report. Good insurance is crucial to cover the risk of financial damage in case of breakdown or accident and contributes to a worry-free driving experience with your business youngtimer.
Frequently asked questions
When is a car officially a youngtimer?
A car is considered a youngtimer as soon as it is exactly 15 years old, calculated from the date of first registration on the vehicle registration certificate.
How is the market value of a youngtimer determined?
The market value is the car's value in commercial trade. This can be demonstrated via an official valuation report or a recognised price list.